
Retail businesses constantly balance opportunity against cash flow. A promising product line may require upfront inventory. A growing store may need additional staff. Seasonal demand may create a temporary need for working capital. In each situation, access to suitable financing can influence how quickly a business responds.
For some retailers, revenue based business funding may offer an approach worth exploring because repayment can be connected to sales performance. Meanwhile, retail store funding can refer more broadly to capital used for the needs of a physical or retail-focused operation.
Understanding the differences between funding approaches can help owners make decisions based on actual business circumstances rather than short-term pressure.
Start With the Business Need
The first step is not choosing a financing structure. It is identifying the problem that requires capital.
A retailer seeking retail store funding should determine whether the money is needed for inventory, renovation, expansion, operating expenses, technology, staffing, or another purpose.
Separate Essential Costs From Growth Plans
Not every expense deserves financing. Essential operational costs may have a different priority from optional improvements.
Creating two categories can help. The first should cover immediate business requirements. The second can include growth initiatives that may produce additional revenue over time.
This distinction makes retail store funding easier to evaluate because the owner can connect each dollar of financing to a specific business objective.
How Revenue-Linked Repayment Works
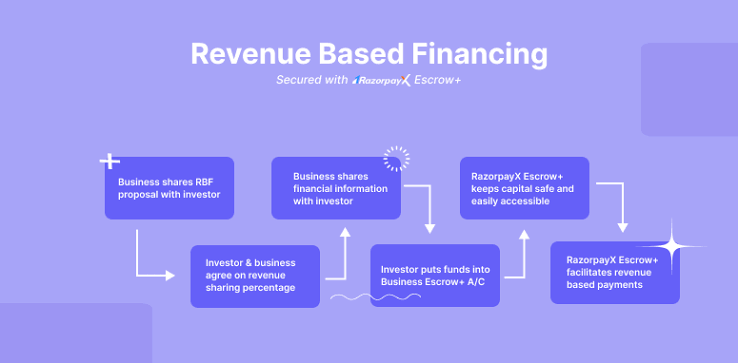
The central idea behind revenue based business funding is that repayment can be tied to a portion of business revenue rather than relying solely on one fixed payment schedule.
For a retailer with changing monthly sales, this structure may provide a different cash-flow profile. However, business owners should never assume that variable repayment automatically means lower overall costs or lower risk.
The specific agreement matters.
Look Beyond the Headline Amount
When evaluating revenue based business funding, consider the complete financial commitment. Review how revenue is defined, how repayments are calculated, the expected repayment period, and whether additional obligations apply.
A financing arrangement should be understandable before it is accepted. If the terms are unclear, the owner should seek clarification before proceeding.
When Retail Funding Can Support Growth
The value of retail store funding depends largely on how effectively the capital is used.
Suppose a retailer identifies a recurring stock shortage during a high-demand period. Additional working capital could allow the business to maintain better inventory levels. In another situation, financing could support a store redesign intended to improve customer flow.
Measure the Expected Outcome
Before using retail store funding, establish a realistic objective. Instead of simply saying that additional capital will help the business grow, identify what success should look like.
That might involve increased inventory turnover, stronger sales, improved operating efficiency, or the ability to serve more customers.
This approach makes it easier to determine whether the financing created meaningful value.
Why Cash Flow Matters
Cash flow is particularly important when considering revenue based business funding. Retail sales can rise and fall because of seasonality, consumer behavior, local conditions, and product demand.
Owners should therefore model several scenarios rather than relying on one optimistic forecast.
Test Strong and Weak Sales Periods
Estimate what repayment could look like during a strong month and then consider what happens if revenue falls.
This exercise can help determine whether revenue based business funding remains manageable during slower periods. It can also highlight whether the business needs a larger cash reserve before taking on additional obligations.
Creating a Smarter Financing Plan
A thoughtful financing strategy combines planning with regular monitoring. Owners using retail store funding should track where the capital goes and compare actual results with their original expectations.
If the money was intended for inventory, monitor sales and stock turnover. If it supported improvements, assess whether those changes produced measurable operational benefits.
Similarly, businesses considering revenue based business funding should keep accurate revenue records and regularly review cash flow.
Common Mistakes to Avoid
One common mistake is borrowing more than the business genuinely requires. More capital can create more repayment obligations, so the amount should have a clear purpose.
Another mistake is ignoring slow periods. Retail businesses should account for seasonality before selecting retail store funding or any other financing arrangement.
A third mistake is comparing options solely by the amount received. With revenue based business funding, owners should examine the full repayment structure and how it fits projected revenue.
Conclusion
Financing decisions can shape a retail business's ability to maintain inventory, manage operating demands, and pursue carefully planned growth. Retail store funding can provide useful financial flexibility when the purpose, amount, and repayment capacity have been evaluated carefully.
At the same time, revenue based business funding may offer an alternative structure for businesses whose sales fluctuate throughout the year. Neither approach should be selected automatically. The right decision depends on cash flow, business objectives, revenue patterns, and the specific terms involved.
Ultimately, responsible financing begins with a clear question: how will the capital strengthen the business, and can the business comfortably support the resulting obligation? Answering that question first can lead to more sustainable financial decisions.

 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)